Retirement Annuity Certificate South Africa: What It Is, Where to Get It, and How to Use It for Your Tax Return
A retirement annuity certificate is the official document your RA provider sends you each year to confirm how much you contributed during the tax year. It is the evidence SARS requires to verify your tax deduction. Without it, you either leave a legitimate deduction unclaimed or risk submitting a figure SARS cannot verify.
If you contribute to a retirement annuity in South Africa, you need this certificate to complete your annual tax return correctly. Your provider is required to issue it after 28 February each year. You should receive it before the SARS filing season opens, usually around July. The certificate shows your total contributions for the year and lets SARS confirm your deduction is accurate.
Understanding how retirement annuities are taxed in South Africa is essential for getting this process right. This article walks you through every step: what the certificate contains, where it goes on your eFiling return, and what mistakes to avoid.
What Is a Retirement Annuity Certificate?
Your RA provider sends you this annual tax certificate to confirm the contributions you made during the previous tax year. You might see it called an IT3(f) certificate, or simply a “contribution certificate.” That distinction matters, because it determines how you capture it on your return.
The IT3(f) is the formal SARS-prescribed certificate format. Providers such as Allan Gray, Sygnia, Ninety One, Old Mutual, and Discovery are all required to issue a certificate that meets SARS standards. But not all of them call it “IT3(f)” in their communications. Some send a PDF with their own branding and refer to it as a “tax certificate” or “retirement annuity contribution schedule.” The content is identical: your fund name, your tax reference number, the tax year covered, and your total contributions.
What the certificate does not capture is the growth on your investment inside the RA. The fund grows free of capital gains tax and income tax while it remains invested. The certificate reflects only what you put in, because that is what determines your deduction. See retirement annuity contribution limits in South Africa for the full breakdown of how those deductible amounts are calculated.
If you contribute to more than one RA, you will receive a separate certificate from each provider. You need to enter each one individually on your tax return. Combining them manually and entering a single total is a common mistake that triggers a SARS query.
Keep your certificate once it arrives. SARS audits are not unusual, and having the original document on hand makes any verification process straightforward.
How Does a Retirement Annuity Work?
A retirement annuity is a long-term savings vehicle designed for retirement investing outside of an employer pension or provident fund. You contribute money regularly or as a lump sum, it is invested in underlying unit trust funds or similar assets, and it grows in a tax-sheltered environment until you retire.
Three tax benefits apply while you are contributing. First, your contributions are deductible up to the limits SARS sets. Second, the investment growth inside the RA is not subject to income tax or capital gains tax while it remains invested. Third, there is no tax on interest, dividends, or rental income earned within the fund during the accumulation phase.
Your RA provider must comply with Regulation 28 of the Pension Funds Act. That rule limits how much of your retirement savings can be held in different asset classes. Here is the simple version: Regulation 28 stops a retirement fund from being too concentrated in a single asset type. It caps equity exposure at 75% and places limits on offshore assets, property, and other categories. This protects your retirement savings from extreme concentration risk, though it also means you cannot put your entire RA into a single aggressive fund.
You can access your RA from age 55 at the earliest, and you do not need to stop working to do so. If you want to understand how a low-cost provider like Sygnia structures its RA, the fees and fund selection available through direct platforms have made this product far more accessible and cost-transparent than it was a decade ago.
One point that many readers miss: an RA is not a savings account you can dip into when cash runs short. The law does not permit early withdrawal except in specific circumstances such as emigration or permanent disability.
How to Get Your Retirement Annuity Certificate
Your retirement annuity certificate is issued automatically by your provider after 28 February each year. You do not need to apply for it. Most providers send it to the email address registered on your account, or make it available in your online portal.
Here is what you should do:
Check your registered email and online portal first. The majority of providers now deliver certificates digitally. Log into your member portal on your provider’s website and look for a “Tax Documents,” “Statements,” or “Certificates” section. Allan Gray, Sygnia, Old Mutual, and most other major providers post tax certificates there from late March or April onwards.
Contact your provider directly if you have not received it by May. Many members report delays when their email address is out of date on the provider’s records. If you have changed email addresses or moved recently, update your contact details so the certificate reaches you before the July filing deadline.
Request a duplicate if the original is lost. Providers can generally reissue certificates on request. Allow a few business days for this, particularly in the peak April-to-June period when providers handle large volumes of requests.
Check for errors before filing. Verify that the contribution total on the certificate matches your own records. If you made ad hoc lump sum contributions during the year, confirm those are included. Errors do occur, and the time to correct them is before you file, not after SARS has processed your return.
If you are managing certificates across multiple providers or unsure whether your RA strategy is optimal, working with a financial adviser for retirement planning can save you both time and money in the long run.
How Much of Your Contribution Is Tax-Deductible?
Your retirement annuity contributions are deductible at 27.5% of the higher of your taxable income or remuneration, up to an annual cap of R350,000. These are the current SARS limits and apply to all qualifying retirement fund contributions, not just RAs.
Here is how that works in practice. If your taxable income for the year is R600,000, your maximum deductible contribution is 27.5% of R600,000, which equals R165,000. If your taxable income is R1,500,000, the 27.5% calculation gives you R412,500, but because the annual cap is R350,000, your deduction is limited to R350,000.
The 27.5% limit applies across all qualifying contributions combined. If you also contribute to an employer pension or provident fund, those contributions count toward the same 27.5% and R350,000 ceiling. You do not get a separate R350,000 deduction for each fund type.
Contributions that exceed the deduction limit are not lost. SARS carries them forward as what are sometimes called “disallowed contributions,” and they can be used to reduce your tax liability when your RA pays out at retirement. This protection prevents genuine double taxation.
A few things worth understanding about this limit:
The deduction reduces your taxable income in the year you make the contribution, which means it effectively reduces your income tax for that year. If you are in a higher tax bracket, the benefit is proportionally larger. A taxpayer in the 41% bracket saves R41 for every R100 contributed (up to the limit). Someone in the 26% bracket saves R26. There is no benefit to contributing more than the cap in a single tax year purely for the current-year deduction, because the excess will not be deductible until a future year.
For a detailed breakdown of how these limits work across different income levels, see a detailed breakdown of retirement annuity contribution limits. You may also want to consider how the 2026 Budget affects retirement and tax planning in the current environment.
Retirement Annuity vs Pension Fund vs Provident Fund: Key Differences
Many people treat retirement annuities, pension funds, and provident funds as interchangeable, but they are meaningfully different products with different rules. The table below captures the key distinctions.
| Feature | Retirement Annuity | Pension Fund | Provident Fund |
|---|---|---|---|
| Who can join | Any individual | Employees of participating employers | Employees of participating employers |
| Employer required | No | Yes | Yes |
| Regulation 28 applies | Yes | Yes | Yes |
| Withdrawal before retirement | Not permitted (except emigration or disability) | Permitted on resignation (subject to tax) | Permitted on resignation (subject to tax) |
| Lump sum at retirement | Up to one-third | Up to one-third | Up to one-third (post-2021 harmonisation) |
| Annuity required at retirement | Yes (on the remaining two-thirds) | Yes (on the remaining two-thirds) | Yes (on the remaining two-thirds, post-2021) |
| Tax on contributions | Deductible up to 27.5% / R350,000 | Deductible up to 27.5% / R350,000 | Deductible up to 27.5% / R350,000 |
The biggest practical difference is accessibility. An RA is the only option for self-employed individuals or anyone whose employer does not offer a fund. A pension or provident fund requires employer participation. On withdrawal rules before retirement, RAs are more restrictive, which many self-employed people find off-putting. That restriction is also the feature that keeps retirement savings intact.
For a closer look at how employer-linked products work in practice, how a provident fund like Momentum works is worth reading alongside this article.
How to Use Your Retirement Annuity Certificate on Your SARS Tax Return
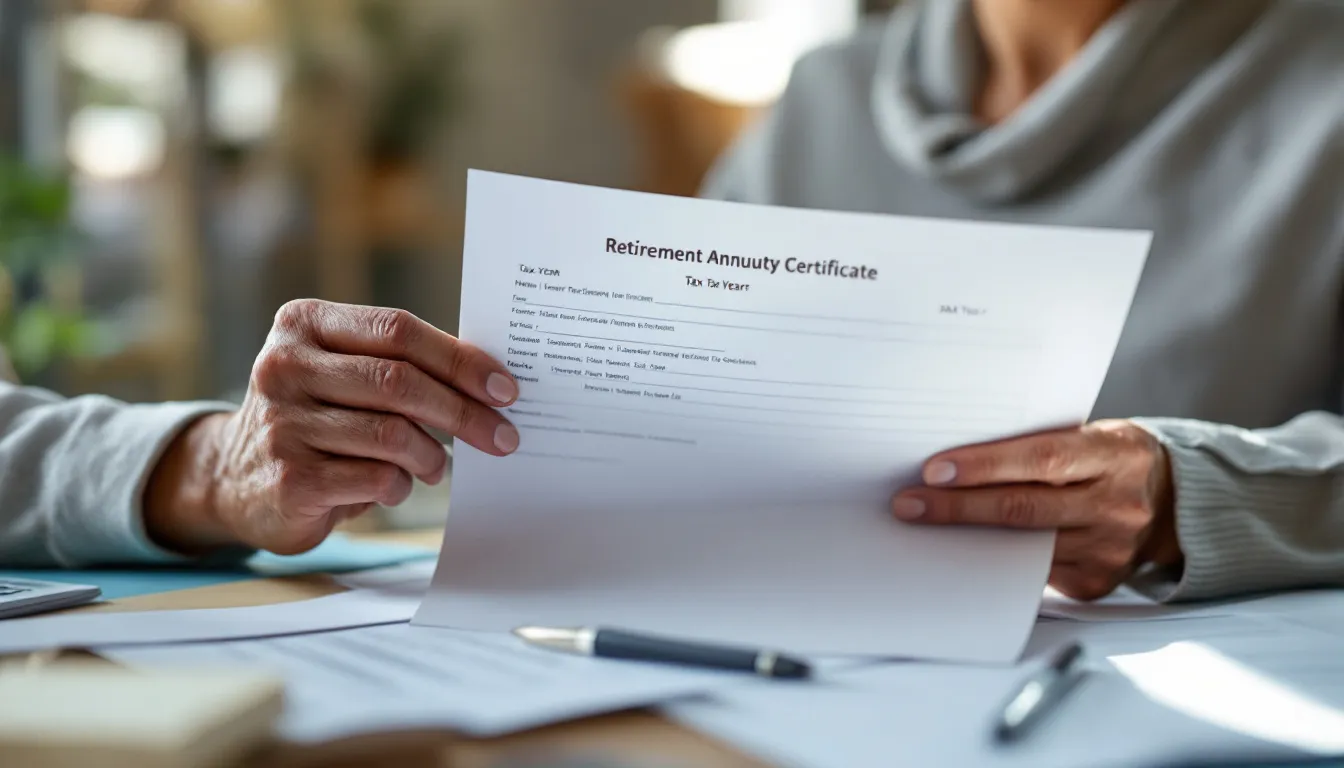
Your retirement annuity certificate feeds directly into the deduction you claim on your annual tax return. On SARS eFiling, this is captured in the “Retirement Fund Contributions” section of your ITR12 return.
Follow these steps:
-
Log into your SARS eFiling account at efiling.sars.gov.za and open your ITR12 return for the relevant tax year.
-
Confirm that the “Retirement Annuity Fund Contributions” section is enabled. On the return, there is a section where you indicate what income and deduction types apply to you. Make sure the retirement fund contributions section is ticked so that the relevant fields appear.
-
Locate the RAF contribution fields. Inside the return, you will find a section labelled “Contributions to retirement funds.” Here you enter the total contributions confirmed on your certificate, not an estimated figure.
-
Enter each certificate separately if you have more than one RA. SARS expects you to reflect the contribution from each fund individually. Do not add them together and enter a single combined figure unless the form explicitly instructs you to.
-
Cross-check the total against your 27.5% limit. If your contributions are below the cap, the full amount is deductible. If they exceed the cap, SARS will carry the excess forward automatically, but you should still enter the actual contribution figure from your certificate.
-
Save and file. Once all sections of your ITR12 are complete, review the calculation to confirm your taxable income has reduced by the expected deduction amount before submitting.
If your employer also contributes to a pension or provident fund on your behalf, those amounts appear on your IRP5 and are already included in the SARS system. Your RA certificate covers contributions you made yourself, outside of payroll.
For context on tax efficiency across different products, how a tax-free savings account compares to a retirement annuity for tax efficiency is a useful parallel read. And if you are unsure whether your retirement income will be taxable later, whether retirement annuities are taxable in South Africa addresses that directly.
What Happens to Your Retirement Annuity When You Retire?
When you retire from your RA, you can take up to one-third of the accumulated value as a lump sum and must use the remaining two-thirds to purchase an annuity. You can access your RA from age 55 onward, and you do not need to stop working to do so.
The lump sum is subject to the SARS retirement lump sum tax table. The first R550,000 of your total retirement lump sums (across your lifetime) is tax-free. If your total RA value is below R247,500 at retirement, you may take the entire amount as a lump sum. Above that threshold, the two-thirds annuity requirement applies.
For most people, the most consequential decision at retirement is not the lump sum. It is choosing between a living annuity and a life annuity for the two-thirds portion. A living annuity keeps your capital invested and lets you draw an income between 2.5% and 17.5% of the fund value per year; the remaining balance can pass to your beneficiaries. A life annuity pays a guaranteed income for life in exchange for your capital, so there is no residual estate value but also no risk of running out of money.
How to choose between a living annuity and a life annuity is a decision that deserves careful thought, ideally with professional guidance. For a broader explanation of how annuity products work, what an annuity is and how it works is a good starting point.
The drawdown rate you choose on a living annuity is one of the most important variables in determining whether your income is sustainable throughout retirement. Taking too much too early is a risk that many retirees underestimate.
Frequently Asked Questions
These are the questions South Africans ask most often about retirement annuity certificates, contributions, and how the product fits into a broader retirement plan. Answers are concise and intended as general information, not personal financial advice.
What is a retirement annuity certificate?
A retirement annuity certificate is an official document issued by your RA provider after the end of each tax year, confirming the total contributions you made during that year. You use it to claim your tax deduction on your SARS ITR12 return. It is sometimes called an IT3(f) certificate.
How does a retirement annuity work?
A retirement annuity lets you invest for retirement in a tax-sheltered environment, outside an employer fund. Contributions are deductible up to prescribed limits, the investment grows free of tax while invested, and you access the funds from age 55 onward. The underlying investments must comply with Regulation 28.
When can someone claim or access their retirement annuity?
You can access your retirement annuity from age 55. Early withdrawal is not permitted unless you emigrate from South Africa, become permanently disabled, or in limited other prescribed circumstances. You do not need to have stopped working to access the fund from age 55.
What are the contribution limits for a retirement annuity in South Africa?
The deductible contribution limit is 27.5% of the higher of your taxable income or remuneration, capped at R350,000 per year. This limit applies across all qualifying retirement fund contributions, including employer funds. Contributions above the limit are carried forward and can reduce tax at retirement.
How much can be withdrawn from a retirement annuity?
At retirement, you may withdraw up to one-third of your RA as a lump sum. If your total RA value is below R247,500, you may take the full amount as a lump sum. The first R550,000 of lifetime retirement lump sums is tax-free. The remaining two-thirds must be used to purchase an annuity.
What is the difference between a pension fund and a retirement annuity?
A pension fund is linked to employment; your employer sponsors the fund and contributions typically come from both employer and employee. A retirement annuity is available to anyone, including the self-employed, with no employer required. Both are subject to Regulation 28 and the same contribution deduction limits.
How does a provident fund compare to a retirement annuity?
A provident fund, like a pension fund, is employer-linked and not available to the self-employed. Following the 2021 harmonisation, provident fund members are now subject to the same one-third lump sum and two-thirds annuity rule as pension and RA members, removing the main historical distinction.
What are current payout rates for retirement annuities?
Payout rates on life annuities depend on your age, gender, prevailing interest rates, and the provider’s pricing. They vary materially between providers and change regularly. The only reliable way to compare current rates is to obtain a personalised illustration from a licensed financial adviser or directly from multiple providers.
How do unit trusts differ from retirement annuities?
A unit trust is a direct investment with no contribution deduction and no restriction on access. An RA wraps similar underlying funds in a tax-advantaged structure, but restricts access until age 55. You get a tax deduction on contributions and tax-sheltered growth inside an RA, but you sacrifice liquidity. For modelling how these choices affect your long-term outcome, a retirement planning tool can help.
What are the fees associated with specific retirement annuity providers?
Fees vary significantly between providers and between fund options within the same provider. Administration fees, underlying fund management fees, and adviser fees (where applicable) all apply. Lower-cost platforms generally charge below 1% per annum in total, while traditional tied-agent products can be considerably more. Ask for a total expense ratio (TER) and any advice fee disclosed separately before committing.
Are retirement annuities taxable in South Africa?
Contributions to a retirement annuity reduce your taxable income during the contribution phase. The investment grows tax-free inside the fund. At retirement, lump sums are taxed according to the SARS retirement lump sum table (with the first R550,000 tax-free), and ongoing annuity income is taxed as normal income. Understanding how inflation erodes retirement savings in South Africa is equally important when planning your drawdown.
What tax benefits come with contributing to a retirement annuity?
Three tax benefits apply: contributions are deductible up to the 27.5% and R350,000 limits, investment growth inside the fund is not subject to income tax or capital gains tax, and lump sums at retirement benefit from the favourable SARS retirement lump sum table. These benefits make the RA one of the most tax-efficient savings vehicles available in South Africa.
The Bottom Line on Retirement Annuity Certificates
Your retirement annuity certificate is a straightforward document with a specific job: it confirms your contributions and enables your SARS tax deduction. Get it from your provider’s portal after 28 February each year, check it for accuracy, and enter the figure in the retirement fund contributions section of your ITR12 on eFiling.
The deduction is real and meaningful. At 27.5% of taxable income up to R350,000, it can reduce your tax bill by tens of thousands of rands per year if you are a consistent contributor. Missing it by failing to obtain or correctly capture your certificate is an avoidable loss.
Beyond the annual certificate, the decisions that matter most are how much you contribute, what you invest in inside the RA, and how you structure your income at retirement. Those decisions benefit from proper planning. If you are unsure whether your current RA strategy is working as hard as it should, speaking to a financial adviser about retirement planning is the most direct way to find out.
This article provides general information about retirement annuities and the South African tax system. It is not personal financial advice. Your individual circumstances will determine what is appropriate for you, and a licensed financial planner can help you assess your specific position.